
 Contatto
 Come acquistare

Consegna
Guida all'acquisto
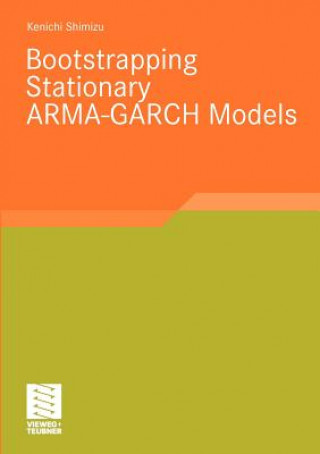
Bootstrapping Stationary ARMA-GARCH Models
 Inglese
 125 b
Fino a 30 giorni per il reso
I clienti hanno acquistato anche


 /
 In brossura
 13.39
€


 /
Rigido
39.59
€

 /
In brossura
48.49
€


Bootstrap technique is a useful tool for assessing uncertainty in statistical estimation and thus it is widely applied for risk management. Bootstrap is without doubt a promising technique, however, it is not applicable to all time series models. A wrong application could lead to a false decision to take too much risk. Kenichi Shimizu investigates the limit of the two standard bootstrap techniques (the residual and the wild bootstrap) when these are applied to the conditionally heteroscedastic models, such as the ARCH and the GARCH models. The author shows that the wild bootstrap usually does not work well when one estimates conditional heteroscedasticity of Engle´s ARCH or Bollerslev´s GARCH models while the residual bootstrap works without problems. Together with the theoretical investigation simulation studies from the application of the proposed bootstrap methods are demonstrated.


Informazioni sul libro
Inglese
Categorie

Regala questo libro oggi stesso
È facile
1 Aggiungi il libro al carrello e scegli la consegna come regalo 2 Ti invieremo subito il buono 3 Il libro arriverà all'indirizzo del destinatarioPotrebbe interessarti anche




 /
Rigido
128.89
€


Ciao! Sono Libroamiko, il tuo consulente di libri.
Come posso aiutarti?