 Contatto
 Come acquistare
Consegna
Guida all'acquisto
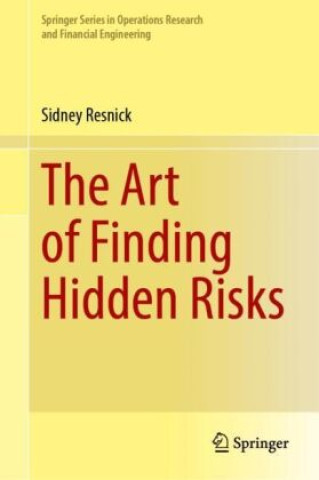
The Art of Finding Hidden Risks
 Inglese
 155 b
Fino a 30 giorni per il reso
I clienti hanno acquistato anche











 /
 In brossura
 14.39
€




This text gives a comprehensive, largely self-contained treatment of multivariate heavy tail analysis. Emphasizing regular variation of measures means theory can be presented systematically and without regard to dimension. Tools are developed that allow a flexible definition of "extreme" in higher dimensions and permit different heavy tails to coexist on the same state space leading to "hidden regular variation" and "steroidal regular variation". This emphasizes when estimating risks, it is important to choose the appropriate heavy tail. Theoretical foundations lead naturally to statistical techniques; examples are drawn from risk estimation, finance, climatology and network analysis. Treatments target a broad audience in insurance, finance, data analysis, network science and probability modeling. The prerequisites are modest knowledge of analysis and familiarity with the definition of a measure; regular variation of functions is reviewed but is not a focal point.


Informazioni sul libro
Inglese
Categorie

Regala questo libro oggi stesso
È facile
1 Aggiungi il libro al carrello e scegli la consegna come regalo 2 Ti invieremo subito il buono 3 Il libro arriverà all'indirizzo del destinatarioPotrebbe interessarti anche


 /
In brossura
40.59
€








 /
In brossura
10.49
€


Ciao! Sono Libroamiko, il tuo consulente di libri.
Come posso aiutarti?